1031 Exchange for Farmland and Agricultural Property in 2026: What Qualifies, What Doesn't
Can you use a 1031 exchange for farmland?
Yes. Farmland, ranchland, orchards, vineyards and farm buildings are real property, so a sale can be rolled into another real property held for investment or business use without current tax on the gain. What changed in 2018 is everything that is not real property: tractors, combines, livestock and harvested grain are out.
This guide is about the farm-specific questions, not the mechanics. If you need the general rules first, start with our 1031 exchange rules guide. The statute is 26 U.S.C. 1031, and the definition of real property that the IRS uses is in Treas. Reg. 1.1031(a)-3. I could not open every page on the IRS site from my research environment, so I cite those sources for the rule and ask you to confirm the current text with your adviser. This is U.S. federal tax law as of November 2026.
Two threshold tests decide whether your farm is even eligible. The first is purpose: the land must be held for investment or for productive use in a trade or business. A farmer working the ground qualifies. A landlord on a cash lease qualifies. Someone who bought acreage to subdivide and flip does not, because property held primarily for sale is excluded by the statute.
The second test is the replacement. It also has to be real property you will hold for investment or business use, and it can be in another state and a different type. Cropland for ranchland works. Cropland for a rental apartment building works too, which matters when the heirs have no interest in farming. For the identification mechanics, see our three-property and 200% rule guide.
What parts of a farm count as like-kind real property?
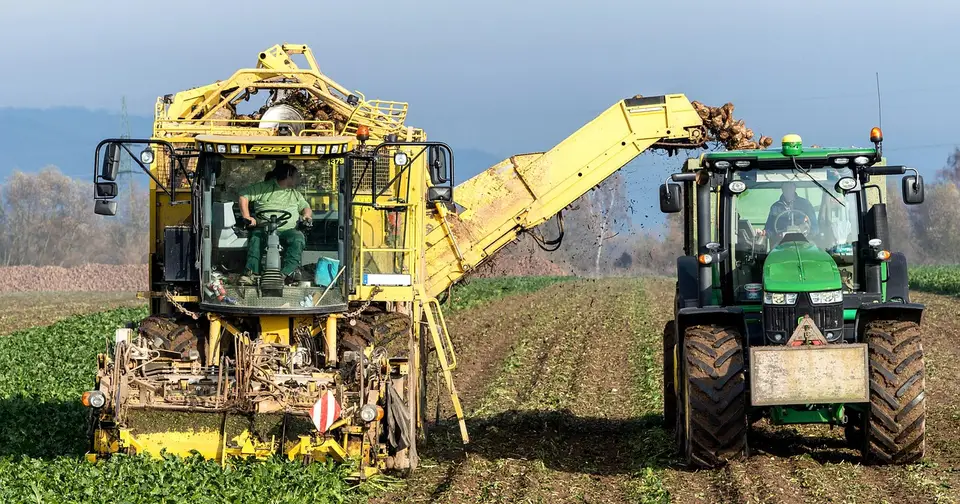
Land and anything permanently attached to it generally qualify, along with growing crops and some land-based rights; machinery, livestock and harvested crops do not. The table sorts the common pieces of a farm sale.
| Asset | 1031 status (2026) | Note |
|---|---|---|
| Cropland, pasture, ranch | Qualifies | Must be held for use or investment |
| Orchards, vineyards, timber | Generally qualifies | Standing trees and bearing plants go with the land |
| Barns, shops, fences | Qualifies if real property | Allocate in the closing statement |
| Grain bins, single-purpose structures | Check with CPA | Often depreciated as equipment |
| Growing crops, unharvested | Generally qualifies | Treated as part of the land |
| Harvested grain, inventory | Does not qualify | Sale is ordinary income |
| Tractors, combines, implements | Does not qualify | Taxable sale; recapture |
| Breeding and dairy livestock | Does not qualify | Taxable; gain may be section 1231 |
| Farmhouse you live in | Does not qualify as exchange property | Home-sale exclusion may apply |
| Water rights, mineral rights | Depends on state law and rights type | Needs advice |
The farmhouse is the piece people forget. A personal residence is not investment or business property, so you cannot put it in the exchange. Instead the home-sale exclusion under section 121 (up to $250,000, or $500,000 for joint filers, if you meet the ownership and use tests) may cover that portion, and the rest of the price goes to the exchange. Your closing team has to allocate the price, and the allocation should be defensible: appraisals beat round numbers.
IRS Publication 225, the Farmer’s Tax Guide, covers how farm sales are reported, and Publication 544 covers sales and exchanges of business property. I could not confirm page-level text for either in this session, so treat them as the places to look, not a quoted authority.
Why did farm equipment stop qualifying, and what does that cost you?
The Tax Cuts and Jobs Act limited section 1031 to real property for exchanges completed after December 31, 2017, so equipment and livestock are now taxable when you sell or trade them. Before that, farmers routinely swapped a worn combine for a newer one and deferred the gain.
The practical cost is depreciation recapture. If you took bonus depreciation or section 179 deductions on a tractor, your tax basis may be near zero, so nearly the full sale price is gain. That gain on depreciable personal property is generally recaptured as ordinary income, not capital gain. Our depreciation recapture guide explains the difference between section 1245 and section 1250 property.
The offset is on the buying side. Since 2025, legislation has restored 100% bonus depreciation for qualifying new and used property acquired after January 19, 2025, and section 179 limits have risen. That does not erase the sale gain, but a farm replacing equipment in the same year can often deduct most of what it buys. I would check the current law with a CPA before planning around it, because limits are indexed and phase out.
Two farm-specific wrinkles. Gain on equipment is usually not eligible for the farm income averaging election on Schedule J, which generally excludes land but can include other farm business property gain; ask your preparer. And a sale of equipment bundled in a farm sale needs its own price, because a lump sum invites the IRS to allocate for you.
Composite example: the combine that turned into boot
This is a composite built from common patterns, not a real client. A couple in the Midwest sells 160 acres of cropland, a machine shed and a grain bin for $1,600,000, with an adjusted basis of about $300,000. Separately they agree to sell a tractor and combine for $210,000; both are fully depreciated.
Their closing attorney drafts one contract at $1,810,000 and tells the intermediary to hold everything. They buy replacement land for $1,810,000 and assume it is all deferred. It is not. The $210,000 attributable to equipment is not like-kind to land, so it is boot, taxable now, and the recapture is ordinary income. At an assumed 32% federal bracket that is roughly $67,000 before any state tax, on top of the land gain they properly deferred.
The fix was cheap and available: list the equipment separately at the start, sell it outside the exchange, and let the replacement equipment purchase carry a first-year deduction. Our guide on boot in a 1031 exchange shows how the taxable portion is calculated.
What about water rights, mineral rights and growing crops?
Unharvested crops are generally treated as part of the land, while water and mineral rights qualify only when they count as real property under your state’s law and the facts of how they are held. This is the corner of ag exchanges where I would insist on written advice.
Growing crops are the easy one. Under the real-property regulations, unsevered natural products of land such as growing crops, plants and timber are part of the real property until severed. Harvested grain and crops in the bin are inventory and cannot be exchanged.
Water rights are state-law territory. In prior-appropriation states, a perpetual water right can be real property that is transferred by deed, and IRS rulings have treated some as like-kind to land. Other rights, such as short-term or contract-based water deliveries, may not qualify, and there is a court decision that went against a taxpayer who swapped water for farmland. A private letter ruling applies only to the taxpayer who asked for it. If a meaningful part of the value of your property is water, get a tax opinion first.
Mineral rights follow a similar logic: a severed, perpetual interest in oil, gas or minerals is generally real property, while a production payment or short-term lease income stream may not be. Reserving minerals from a land sale is a common structure and does not by itself break the exchange.
Inherited farm: step-up in basis vs 1031 exchange, which wins?
If you intend to keep the farm until death, the step-up in basis usually beats a 1031 exchange, because the heirs’ basis resets to fair market value and the deferred gain is never taxed. A 1031 exchange only defers; the old basis rides along into the replacement property.
Under section 1014, property included in a decedent’s estate generally takes a basis equal to its fair market value at the date of death (or the alternate valuation date). A farm with a $300,000 basis worth $3 million becomes a $3 million basis for the children. If they sell soon after, the taxable gain is small. Depreciation recapture on old buildings also resets.
So the question is who is selling and when. An older owner who wants to stop farming but does not want to sell can compare three paths: hold and let the heirs sell with a stepped-up basis; sell now and pay the tax; or exchange into another property and defer. The exchange makes sense when you want different property while you are alive, such as moving from labor-intensive row crops to a leased parcel, or into something the children will actually manage. It makes less sense as a way to avoid a sale you never intended to make.
| Path | Tax on the gain | Basis for heirs | Best when |
|---|---|---|---|
| Sell now | Taxed now | n/a | You need cash or have losses |
| 1031 exchange | Deferred | Carryover from old farm | You want a different property |
| Hold until death | Never taxed (basis resets) | Stepped up to value | Heirs keep or sell later |
| Gift during life | Not taxed to you | Carryover (no step-up) | Rarely best for appreciated land |
Estate tax is the other side of the ledger. The federal basic exclusion amount is $15 million per person for 2026 as I understand current law, so many farm estates fall under it, though large operations and states with their own estate or inheritance taxes do not. For estates that exceed it, section 2032A special use valuation (a reduction of roughly $1.4 million, indexed, if conditions are met) and section 6166 installment payment can help, with strict material participation and a ten-year recapture trap if heirs stop farming. Confirm the current exclusion and valuation limits on the IRS estate tax pages before planning around them.
How do conservation easements, CRP and farm program payments affect the exchange?
They sit alongside the exchange rather than inside it: easement proceeds and program payments have their own tax rules, and transfers of USDA contracts need approval. Mixing them in is where deals stall.
A sale of a conservation easement, for example through a purchase-of-development-rights program or the NRCS Agricultural Conservation Easement Program, is a partial sale of your property rights. It can create taxable gain that is not deferred just because you also sold the farm. A donation of an easement is a charitable-deduction question with heavy IRS scrutiny of syndicated deals; see our conservation easement deduction guide. Put an easement on the replacement farm before closing and you could reduce the value you are trying to buy, so coordinate with the lender and appraiser.
The Conservation Reserve Program adds a practical layer. CRP contracts run with the land and the producer, transfers need approval from your county FSA office, and early termination can trigger repayment. Annual rental payments are income to you for the year and are not part of the exchange proceeds. Whether they are subject to self-employment tax depends on your situation, so ask your preparer rather than assume.
Two other items a farm CPA will check. Cost-share payments and soil and water conservation deductions can carry recapture rules if you dispose of the land within a set number of years, and that potential generally follows into a replacement property. And buying land with highly erodible soil or wetlands can affect your eligibility for USDA programs; check the compliance certification with FSA before you close.
How do farm seasons break the 45-day and 180-day deadlines?
The 45-day identification and 180-day closing clocks do not pause for harvest, planting, lease terms or a slow ag lender, so the schedule has to be built around the farm calendar. The deadlines are the same as for any exchange, but the market is thinner.
Farm sales cluster in fall and winter, after harvest, and a lot of sellers prefer a closing date that does not strand a tenant mid-lease. If you close on the relinquished farm in November, the 180-day window runs into spring, and if it crosses your tax return due date, the earlier of the two applies unless you extend. Missing that quirk is a classic way to lose a deferral on paper.
Practical habits that help:
- Shop first. Find two or three candidate farms and a lender conversation before you list yours. Ag financing is slower than residential.
- Identify generously. The three-property rule gives you backups; use them. Farms often fall out over survey, access or water issues.
- Check leases. An existing cash-rent or crop-share lease can bind a buyer for the season. Read it before you set a closing date.
- Consider a reverse exchange. Buying the replacement first through an accommodation titleholder takes pressure off timing but costs more; expect higher legal and titleholder costs.
- Check state rules. Nonresident withholding, transfer taxes and foreign ownership limits on agricultural land differ by state.
If you want to understand whether farmland as an investment fits your plan at all, our farmland investing guide looks at returns and structures. If you plan to take cash and spread the tax instead, the installment sale guide compares that route.
What should you do before listing the farm?
Build a short pre-sale file with your CPA, a qualified intermediary and an ag attorney before you sign a listing agreement, because the exchange must be set up before closing. Everything below is cheaper in October than in December.
- Map the assets. List land, buildings, equipment, livestock, crops, water, minerals and USDA contracts, with tax basis for each.
- Decide the exit. Compare sell, exchange, hold-for-step-up and installment, using your age, your heirs and your cash needs.
- Engage the intermediary early. The intermediary has to be in place before you close.
- Write the allocation into the contract. Price land, equipment, crops and the home separately.
- Call FSA. Confirm what happens to CRP, base acres and program enrollment on transfer.
- Plan the equipment. Decide whether to replace it, and time the purchase with the tax year in mind.
This article is general information about U.S. federal tax law as of November 2026, not tax or legal advice. Rules vary by state and by the facts of your farm. Primary-source pages were cited but some could not be opened during research, so confirm the current text with a CPA or attorney who works with agricultural clients before acting.
Can you use a 1031 exchange for farmland?
Yes. Farmland, ranchland, orchards, vineyards, farm buildings and, depending on state law, water and mineral rights are real property and can be exchanged for other real property held for investment or business use. The land must be held for productive use or investment, not for resale, and the usual 45-day and 180-day clocks apply.
Can I include my tractor or combine in a 1031 exchange?
No. Since the Tax Cuts and Jobs Act, section 1031 covers only real property for exchanges after 2017. Equipment and livestock are sold or traded in a taxable transaction, with depreciation recapture usually taxed as ordinary income, though bonus depreciation or section 179 on replacement equipment can offset it.
Are growing crops part of a farm 1031 exchange?
Unharvested crops still growing on the land are generally treated as part of the real property. Harvested grain, stored crops and inventory are not real property and cannot be exchanged. Ask your closing team to allocate the price among land, crops and personal property in writing.
Do water rights and mineral rights qualify for a 1031 exchange?
They can, depending on how your state classifies them and how they are held. Perpetual water rights tied to the land and severed mineral interests have been treated as real property in IRS rulings, but a ruling is addressed to one taxpayer. Get a written opinion before relying on it.
Is it better to do a 1031 exchange or hold the farm until death for the step-up in basis?
If you plan to keep the farm, holding until death usually wins because heirs receive a basis equal to fair market value and the deferred gain disappears. A 1031 exchange only defers gain and carries your old basis forward. Exchange when you want a different property now, not to avoid a sale you never plan to make.
Can I exchange farmland for a farm in another state?
Yes. Like-kind for real property is defined broadly, so a Nebraska ranch can be swapped for Texas cropland. Check each state's rules on withholding, nonresident tax, and foreign-ownership limits on agricultural land before you sign.
What happens to CRP contracts and farm program payments when I sell?
Conservation Reserve Program contracts and farm program enrollments are tied to the land and operator through your county FSA office, and a transfer needs FSA approval. Program payments are income to you; they are not part of the exchange. Contact FSA before listing the farm.
Can I put a conservation easement on the replacement farm?
You can, but selling an easement is a partial sale of the property with its own taxable gain, and donating one is a separate deduction question with heavy IRS scrutiny. Do not mix an easement into the exchange without tax counsel.
How hard is the 45-day identification rule for farmland?
Harder than for city property. Few farms trade at any moment, sellers often want a harvest or lease-end closing date, and financing for ag land moves slowly. Many owners line up candidates before they list, or use a reverse exchange so the replacement is already owned.
Does a 1031 exchange avoid depreciation recapture on farm buildings and grain bins?
Only to the extent the replacement is real property of equal or greater value with no boot. Certain single-purpose agricultural structures are depreciated as equipment, and any part treated as non-real property can create taxable recapture. Your CPA should map each improvement.
관련 글
1031 Exchange Boot in 2026: Cash Boot, Mortgage Boot, and How Much Gain Gets Taxed
1031 Exchange for Oil and Gas Mineral Rights in 2026: What Qualifies and What Gets Recaptured
Build-to-Suit 1031 Exchange: Using Exchange Proceeds to Build or Improve Replacement Property (2026)
Divorce Property Division: Equitable Distribution vs Community Property 2026
Oilfield Injury Lawyer: What Oil & Gas Workers Need to Know About Legal Claims in 2026