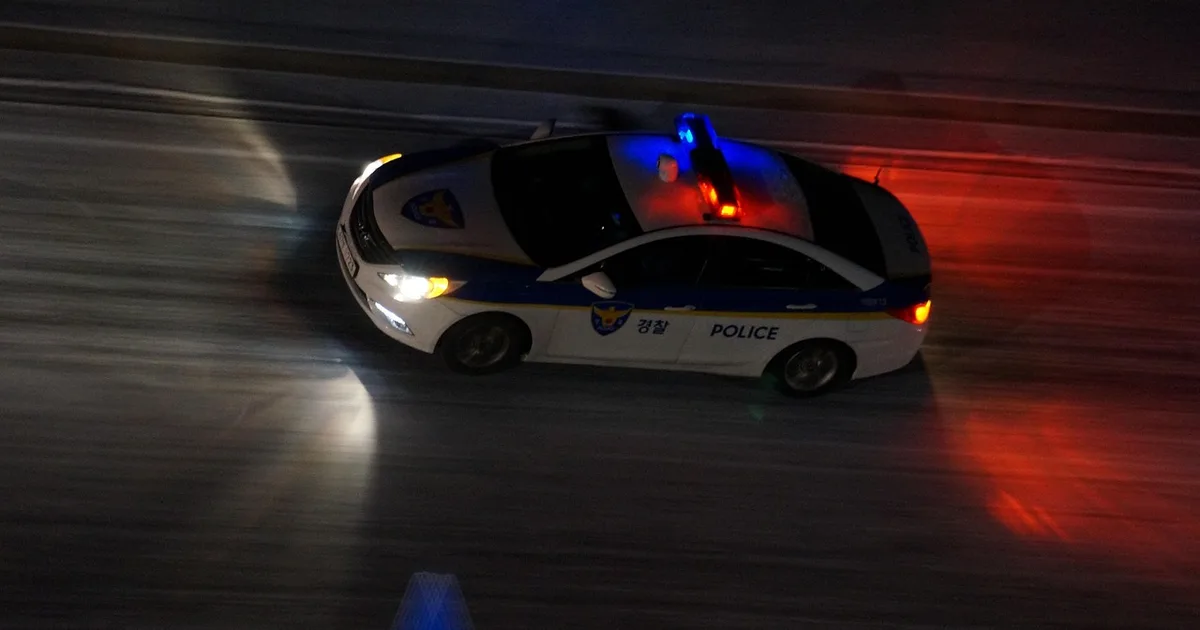
Hit-and-Run Accident Lawyer 2026: What to Do and How to Get Paid When the Driver Flees
What does a hit-and-run accident lawyer do when the driver is never found?
A hit-and-run accident lawyer builds the claim your own insurance company will owe you when the at-fault driver flees. In most cases that means an uninsured motorist (UM) claim, backed by a police report, medical records, and any proof that a second vehicle existed.
That last point is the whole game. When the other driver is a stranger, there is no opposing insurer to argue with, only your own. And your own insurer has every incentive to ask whether the “phantom vehicle” really existed. A lawyer’s job is to answer that question before it is asked.
This guide is general information for U.S. readers, not legal advice. Deadlines and coverage rules change by state, and I flag where I could not verify a statute’s current wording.
What should I do in the first hour after a hit-and-run?
Get safe, call 911, and get a police report number. Everything else, from your UM claim to a possible criminal case against the driver, rests on what you capture in the first hour.
Work through this list in order:
- Move out of traffic if you can, and turn on hazard lights.
- Call 911. Say you were hit by a driver who left. Ask for an officer to come out and for the report number before you leave.
- Write down what you remember before it fades: plate (even partial), make, color, damage you think the car has, direction of travel, time.
- Photograph everything: your car, paint transfer, glass, skid marks, street signs, your injuries.
- Get witness names and phone numbers. A bystander who saw the car is worth more than a perfect photo.
- Get checked by a doctor today, even if you feel fine. Adrenaline hides injuries, and a gap in treatment is the first thing an adjuster points to.
- Notify your insurer that a hit-and-run occurred. Stick to facts and do not guess about speed or fault.
The AAA Foundation for Traffic Safety, which analyzes federal crash data, describes hit-and-run as a growing problem, with most deaths involving people outside vehicles and most happening after dark. That matters for you because darkness makes evidence thinner. Cameras and witnesses are your best friends, so move fast.
How does an uninsured motorist claim work for a hit-and-run?
UM coverage treats the unidentified driver as if they had no insurance, so your own insurer pays your losses up to your UM limits. You are making a first-party claim, which means your insurer is on the other side of the table even though you have been a customer for years.
UM typically covers:
- Medical expenses not paid elsewhere
- Lost wages
- Pain and suffering, in most states
- Property damage, in some states or through collision coverage
| Coverage | What it does in a hit-and-run | Common limit to check |
|---|---|---|
| UM bodily injury | Pays injury losses when the driver is unknown | Your policy’s declarations page |
| UM property damage | Repairs your car in some states, often with a deductible | State-specific |
| Collision | Repairs your car regardless of fault, subject to deductible | Deductible and actual cash value |
| Med-pay or PIP | Pays medical bills quickly, regardless of fault | Often small, state-dependent |
| Health insurance | Pays treatment, but may seek reimbursement | Plan-specific |
If you did not buy UM, the picture changes. Some states require insurers to offer it and make you reject it in writing; others do not require it at all. Pull your declarations page and read it before assuming anything. For a deeper look at how UM and underinsured claims can go wrong with an insurer, see our guide to uninsured and underinsured motorist bad faith claims.
Do I need to prove the other car actually touched mine?
Sometimes yes. A number of states, and many policies, require physical contact between your vehicle and the unidentified one before UM applies. Other states accept independent corroboration instead, such as a disinterested witness or video.
Search results I reviewed describe the landscape as mixed: older commentary counted at least two dozen states with a statutory contact requirement, while others have rejected it or allow the insured to substitute corroborating evidence. These sources are dated, so I would not rely on the count. The practical point is simple: find out which rule your state follows before you give any statement.
Why does this matter?
- If you swerved to avoid a car that cut you off and hit a guardrail, there may have been no contact at all.
- A car that sideswipes a vehicle that then hits you may raise “indirect contact” questions.
- Policies sometimes define “uninsured motor vehicle” more narrowly than the statute allows, and courts in some states strike down the narrower language.
Corroboration is your fallback. A dashcam clip, a traffic camera, a 911 call from another driver, or a restaurant’s exterior camera can turn a “no proof” claim into a covered one.
What deadlines apply after a hit-and-run?
Two clocks run at once: the notice and reporting deadlines in your policy or state law, and the statute of limitations for filing a lawsuit. The first set is usually much shorter and is where good claims die.
Notice and reporting rules. Some states require a prompt police report as a condition of UM coverage for unidentified vehicles. California is the commonly cited example, with commentary describing a requirement to report to law enforcement within 24 hours and give the insurer a sworn statement within a set period afterward. I could not open the statute text, so verify against California Insurance Code section 11580.2 or ask a California lawyer. New York has its own no-fault and unidentified-driver procedures with short notice windows, which a lawyer should walk you through.
Statutes of limitations. The deadline to file suit varies. Three examples, hedged because these laws get amended:
| State | General injury deadline (negligence) | Note |
|---|---|---|
| Texas | 2 years | See Texas Civil Practice and Remedies Code ch. 16 |
| New York | 3 years | No-fault benefit applications have separate, much shorter deadlines |
| Florida | 2 years for accidents on or after March 24, 2023 | Earlier accidents were generally 4 years; see Fla. Stat. 95.11 |
The detail people miss: a UM claim is a contract claim against your insurer, and the policy or state law may measure its deadline differently from the injury lawsuit deadline. Put both dates in your calendar on day one.
Can a lawyer help find the hit-and-run driver?
Sometimes, though the police do the heavy lifting. A lawyer can preserve evidence the police may not prioritize, and a located driver opens a second source of recovery.
Realistic steps include:
- Canvassing for cameras. Businesses, traffic systems, and doorbell cameras often overwrite footage within days. A lawyer can send preservation letters quickly.
- Paint and debris. Parts left at the scene can identify a make and model.
- Witnesses. Interviews right away produce better detail than statements taken months later.
- Tip lines and media appeals. Some jurisdictions publicize serious cases.
- Your own dashcam. Check the card; many cameras record over old clips.
If the driver is found and insured, you may recover from their liability policy and also have UM or UIM coverage as a backstop if their limits are low. If the driver is found and uninsured, your UM claim continues. The time to preserve all of this is now, not after the case has gone cold. Liability on the criminal side is separate: leaving the scene of an injury crash is a crime in every state, and the penalties are up to prosecutors, not to your civil claim.
What mistakes sink hit-and-run claims?
The most common are delay, loose statements, and quietly assuming the insurer will be fair. Here is a composite example, not a real client:
A driver is clipped at night on a two-lane road, feels sore, and goes home. She tells her insurer a day later that “a car hit me” but did not call police because she did not see the plate. Three weeks later her neck pain worsens and she sees a doctor. The insurer notes that there was no police report, no witness, a gap in treatment, and a recorded statement where she said she “might have drifted.” The claim is delayed and discounted.
What went wrong, and how to avoid it:
- No police report. Even without a plate, call. In some states a prompt report is a condition of coverage.
- A recorded statement given too early. You are not required to give a recorded statement to the other side. Your own insurer may ask for cooperation; ask a lawyer how to give it safely.
- Delay in treatment. See a doctor within a day or two and follow through with care.
- Signing a broad medical release. Limit it to relevant records.
- Guessing. “I think I might have been over the line” gets quoted back.
- Taking the first offer before you know your full medical picture.
If your injuries are significant, the same fault and damages arguments covered in our car accident settlement amount guide still apply, just with your own insurer as the payer.
How much do lawyers charge on a hit-and-run case?
Most personal injury lawyers work on contingency, meaning they are paid only if you recover. A common structure is roughly one-third of the recovery before suit and up to around 40% if the case is filed or goes to trial, though this varies by firm and state, and some states regulate fee schedules.
| Fee point | What to ask |
|---|---|
| Percentage | Is it calculated before or after case costs? |
| Costs | Who advances filing fees, experts, records? Are they deducted from your share? |
| Tiers | Does the percentage rise when a lawsuit is filed? |
| Liens | Who negotiates health insurer or hospital liens? |
| Insurer-paid benefits | Is med-pay or PIP counted in the fee base? |
The effect of a lawyer on net recovery is something to test, not assume. A tiny, clear-cut property claim may not need one. A serious injury claim against your own insurer, with a coverage dispute or a contact-rule argument, often does. For the fuller breakdown of rates, costs, and liens, see our guide to personal injury lawyer fees.
Does the claim change if I was walking, biking, or riding a motorcycle?
The core process is the same, but the evidence and coverage questions shift. Pedestrians and cyclists are overrepresented in fatal hit-and-run crashes, according to AAA Foundation analysis, and in many cases UM can respond through a policy in your household even if you were not in a car.
- Pedestrians and cyclists. Look at every household auto policy for UM. Our pedestrian accident lawyer guide covers crosswalk and fault issues.
- Motorcyclists. Many motorcycle policies sell UM separately, and some insurers exclude certain situations. See the motorcycle accident lawyer guide.
- Drunk or distracted drivers who fled. If the driver is later identified, a separate liability case may open. Our guides on drunk driving accidents and distracted driving explain how those claims are proven.
How long does it take, and what should I do this week?
Timelines vary widely, from a few months for a simple UM claim to a year or more if there is a coverage dispute or litigation. Police investigations of unidentified drivers can stay open for a long time without resolution, and your claim should not wait on them.
This week:
- Request the police report number and a copy of the report.
- Pull your policy declarations page and note UM, med-pay, and collision.
- Send your insurer written notice, factual only.
- Save photos, receipts, and a symptom diary.
- Write down every deadline you can identify, then ask a lawyer to confirm them.
- Do not post about the accident on social media.
If the driver turns out to be found, or if your insurer disputes the existence of a second vehicle, that is the moment to bring in counsel, if you have not already.
This article is general information, not legal advice, and no settlement or outcome is guaranteed. Laws, deadlines, and policy terms vary by state and change; verify them with your state’s statutes, your policy, and a licensed attorney. Information current as of November 2026.
Do I need a hit-and-run accident lawyer?
Not for every case, but usually when you were hurt. If you only have minor property damage and your collision coverage pays, you may not. If you have medical bills, missed work, or the insurer is slow-walking an uninsured motorist claim, a lawyer who handles contingency cases is worth a consultation, which is typically free.
Who pays if the driver who hit me is never found?
In most cases your own insurer, through uninsured motorist (UM) coverage if you carry it. Some states also treat an unidentified driver as uninsured by statute. Without UM coverage, you may be limited to health insurance, med-pay or PIP, and any disability benefits.
What should I do right after a hit-and-run?
Get to safety, call 911, and ask for a police report. Photograph the scene, your injuries, and any debris or paint transfer. Write down the plate, vehicle description, direction of travel, and witness names while your memory is fresh, then get medical care the same day.
Does my UM claim require the other car to touch mine?
It can. Many states and policies require physical contact for an unidentified vehicle, while others accept independent corroboration such as a witness. The rule differs by state and policy wording, so read your policy's definition of uninsured motor vehicle and ask a local lawyer.
How soon must I report a hit-and-run to my insurer?
As soon as possible, and many policies and some statutes set tight windows for police reports and written notice. California, for example, is known for a short police-reporting window for unidentified-vehicle claims. Treat the first 24 hours as the target and confirm your state's exact rule.
How long do I have to sue after a hit-and-run?
It depends on the state. Texas generally allows two years for injury claims, New York three, and Florida two for negligence cases arising from accidents on or after March 24, 2023. Your UM contract may set its own, sometimes shorter, deadlines, so check both.
How much does a hit-and-run lawyer cost?
Most personal injury lawyers work on contingency, commonly in the range of one-third of the recovery, rising toward 40% if a lawsuit is filed. You usually pay nothing upfront, but ask how case costs and medical liens are handled before you sign.
Can I be sued or penalized if I flee and later come forward?
Leaving the scene of an injury crash is a crime in every state, and delay does not erase it. If you are the driver who left, speak to a criminal defense lawyer before talking to police or any insurer.
Will a UM claim raise my rates?
Rules vary by state and insurer. Many states restrict surcharges for accidents where you were not at fault, but not all do, so ask your insurer or your state insurance department how a not-at-fault UM claim is treated.
What if I was a pedestrian or cyclist when the driver fled?
UM coverage on your own auto policy or a household member's policy can often apply even when you were not in a car. Pedestrians and cyclists make up most hit-and-run deaths, so look at every policy in your household.
관련 글
Personal Injury Settlement Timeline: How Long a Case Takes in 2026
Traumatic Brain Injury (TBI) Lawyer 2026: A Practical Guide to Claims, Damages, and Settlements
Firefighter Turnout Gear PFAS Lawsuit 2026: Who Can Claim, How It Works, What to Expect
Social Security Disability Lawyer 2026: SSDI vs SSI, the Appeals Ladder, and How Attorney Fees Actually Work
Insurance Bad Faith Lawyer 2026: How to Fight a Wrongful Denial, Delay, or Lowball
